Learn / Position size and liquidation
Risk
Position size and liquidation
Leverage does not change the direction you need to be right. It changes how far the price can move against you before the venue closes the trade for you. That distance is the whole point of writing the number down before you click.
Notional, margin, leverage
Notional is the size of the position. Margin is the collateral you post. Leverage is notional divided by margin. A $10,000 position with $1,000 of margin is 10× leverage. The other $9,000 is not a gift. It is the gap the price is allowed to eat.
A teaching formula
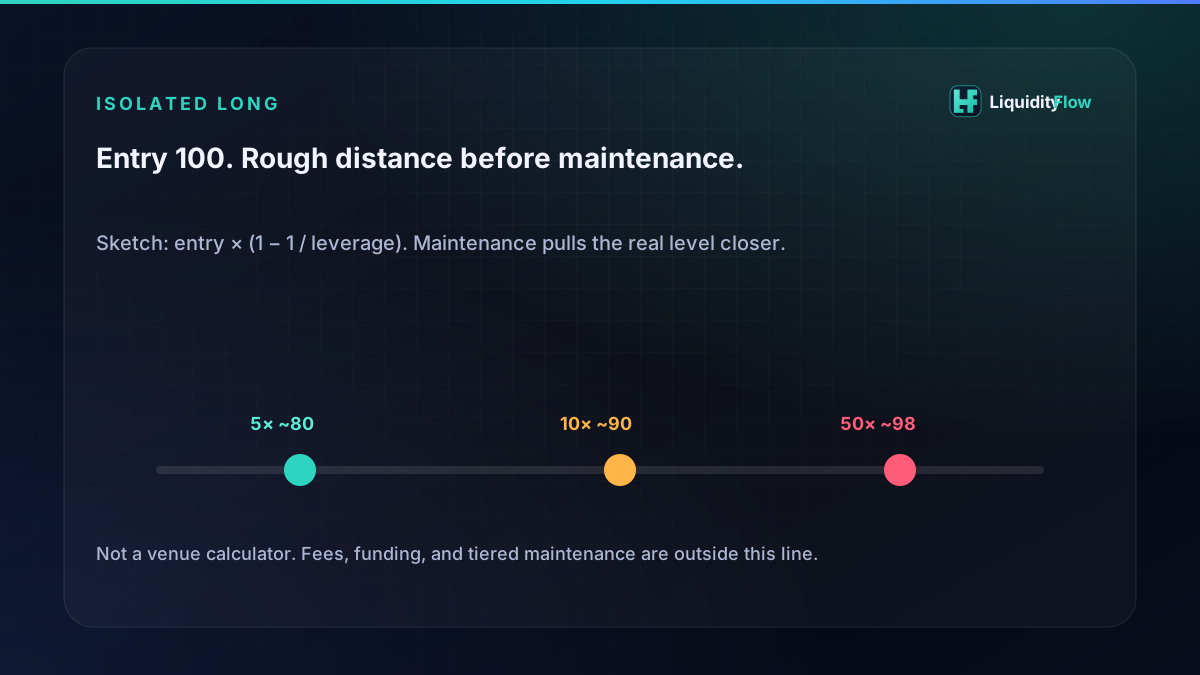
For a long isolated linear perpetual, the cost-free model is entry times (1 minus 1 divided by leverage), divided by (1 minus the maintenance rate). Maintenance is calculated on notional at the liquidation mark, not at entry. At 10× with 0.5% maintenance, the model is about 9.55% below entry; at 50×, about 1.51%. Fees, funding, tiers and added margin change the real result.
Shorts mirror this above the entry. These sketches ignore fees, funding, insurance funds, tiered maintenance, and the difference between last price and mark price. Real venues liquidate on the mark, and the maintenance rate depends on notional. Use the venue’s own calculator for an order. Use ours on the practice desk only to see the shape of the math.
What to decide first
Decide the dollar loss you can accept, then the distance to invalidation, then the size. Traders who start from the leverage slider do this backwards. A wide stop with small leverage and a tight stop with high leverage can lose the same dollars. They do not feel the same, because the tight one gets closed by noise.
Nothing on LiquidityFlow submits an order. If a number on the practice desk and a number on the exchange disagree, the exchange is the one that will liquidate you.
Size it from the loss, not the slider
You can lose $100 and still sleep. The invalidation on your chart is 5% under entry. Notional that loses $100 on a 5% move is $100 / 0.05 = $2,000. At 2× you post about $1,000 of margin. At 10× you post about $200 and the liquidation sits close to that 5% line. The dollar risk was chosen first. The leverage was whatever margin you had left.
Use case: the exchange slider opens at 20×. Ignore it until the notional and the distance are written down. Then set leverage so liquidation is beyond the invalidation, not on top of it. If the venue’s calculator shows a nearer liquidation than this sketch, trust the venue.
Entry 100, isolated long, no maintenance in the sketch: 10× is about 90, 50× is about 98. Add a maintenance haircut and both move up, toward the entry. Shorts mirror the distance above the entry.
Questions
Will this formula match Bitunix, BloFin, or MEXC?
Not exactly. It is an isolated-margin sketch with a fixed 0.5% maintenance assumption so you can see how leverage moves the level. Each venue publishes its own tiers.
Does 100× mean the profit is 100 times larger?
It means gains and losses on the margin are about 100 times the underlying move, until liquidation or until you close. The loss is capped near the margin. The path to that loss is short.